As the international art market adjusts to more selective collecting, the difference between an artwork's estimated value and its ability to attract a buyer is becoming increasingly significant. Behind record-breaking auctions lies a structural problem that collectors cannot afford to ignore: art is considerably easier to acquire than to convert into cash.
The art market has developed sophisticated mechanisms for encouraging acquisition. International galleries cultivate collectors, art fairs concentrate inventory, auction houses generate competitive excitement and digital platforms make artworks accessible to buyers across continents. Yet the infrastructure supporting resale remains considerably less efficient. An artwork purchased in a matter of hours may require months, sometimes years, to find another buyer at an acceptable price.
This imbalance is one of the defining financial characteristics of art ownership.
Unlike publicly traded securities, artworks cannot generally be sold through continuous markets offering transparent prices and immediate execution. Each transaction requires an appropriate buyer, confidence in the work's authenticity and condition, agreement on valuation and, frequently, the involvement of specialist intermediaries.
Recent market developments have made these constraints more visible. According to the Art Basel and UBS Global Art Market Report 2026, worldwide art sales increased by 4% to approximately $59.6 billion in 2025, reversing two consecutive years of decline. Yet the recovery was uneven, concentrated partly among exceptional works at the upper end of the auction market.
As collectors look towards 2027, the central challenge may therefore be less about determining what an artwork is worth than establishing whether that valuation can actually be realised.
The Difference Between Market Value and Market Liquidity
Liquidity describes the ability to convert an asset into cash within a reasonable period without substantially reducing its price. In financial markets, liquidity is supported by frequent transactions, numerous participants and transparent price information.
Art operates differently.
Even where an artist has an established auction history, individual works can vary considerably in quality, scale, period, subject matter, provenance and condition. A recent auction record may provide a useful reference point, but it does not establish an immediately available buyer for another artwork by the same artist.
This distinction becomes especially important when collectors rely on valuations for insurance, estate planning or financial reporting.
An insurance valuation may reflect the estimated cost of replacing an artwork in the retail market. An auction estimate expresses an expectation of the price achievable under particular sale conditions. Neither necessarily represents the amount the owner would receive through an immediate transaction.
The difference between these figures can be substantial.
A collector may possess an artwork valued at £500,000, yet discover that prospective buyers are willing to offer considerably less. The work has not necessarily lost its artistic importance. Its estimated financial value simply exceeds the price that current demand can support.
Such situations expose a central weakness in the treatment of art as an investment asset. A quoted valuation is not equivalent to accessible capital.
Research examining art-market liquidity has emphasised this problem, identifying the probability that an artwork remains unsold as an important measure of market risk. Because artworks lack continuous trading and observable bid-ask quotations, conventional financial liquidity measures cannot be applied directly.
The result is a market in which ownership can be established immediately, but the ability to exit remains uncertain.
What Auction Results Reveal About the Difficulty of Selling
Auction houses provide the clearest publicly observable evidence of art-market liquidity because unsuccessful transactions can be measured alongside completed sales.
The Art Basel and UBS report found that approximately 30% of fine art lots offered at auction worldwide in 2025 remained unsold. Although the proportion improved from 32% in 2024, it still meant that nearly one in three offered works failed to find a buyer at or above the seller's reserve price.
The report also documented considerable variation between market segments and auction houses. Sotheby's, Christie's and Phillips achieved substantially stronger sell-through rates in selected sales, while the broader market remained more challenging.
A bought-in artwork does not necessarily indicate an absence of interest. Potential buyers may have been willing to bid, but not at the level required by the seller.
Nevertheless, the outcome exposes the difference between an owner's expectations and the price available in the market.
The consequences can extend beyond the unsuccessful auction.
Once a work has been publicly offered without selling, prospective buyers gain information about the seller's willingness to transact and the market's apparent reluctance to meet the reserve. This can influence subsequent negotiations, although the effect varies according to the artwork and circumstances.
A particularly revealing example occurred at Sotheby's in May 2025, when Alberto Giacometti's Grande Tête Mince (Grande tête de Diego), carrying an estimate of approximately $70 million, failed to sell.
Christie's also withdrew Andy Warhol's Big Electric Chair, estimated at approximately $30 million, shortly before its planned auction that month.
Neither outcome diminished the established importance of the artists. Both demonstrated that even historically significant works can encounter resistance when seller expectations and market demand diverge.
The contrast with 2026 is instructive. In May, Phillips reported a sold-out New York evening auction totalling $115.2 million including fees. The result demonstrated that competitive demand remained available for appropriately positioned works.
Taken together, these examples suggest that liquidity is highly selective rather than uniformly absent.
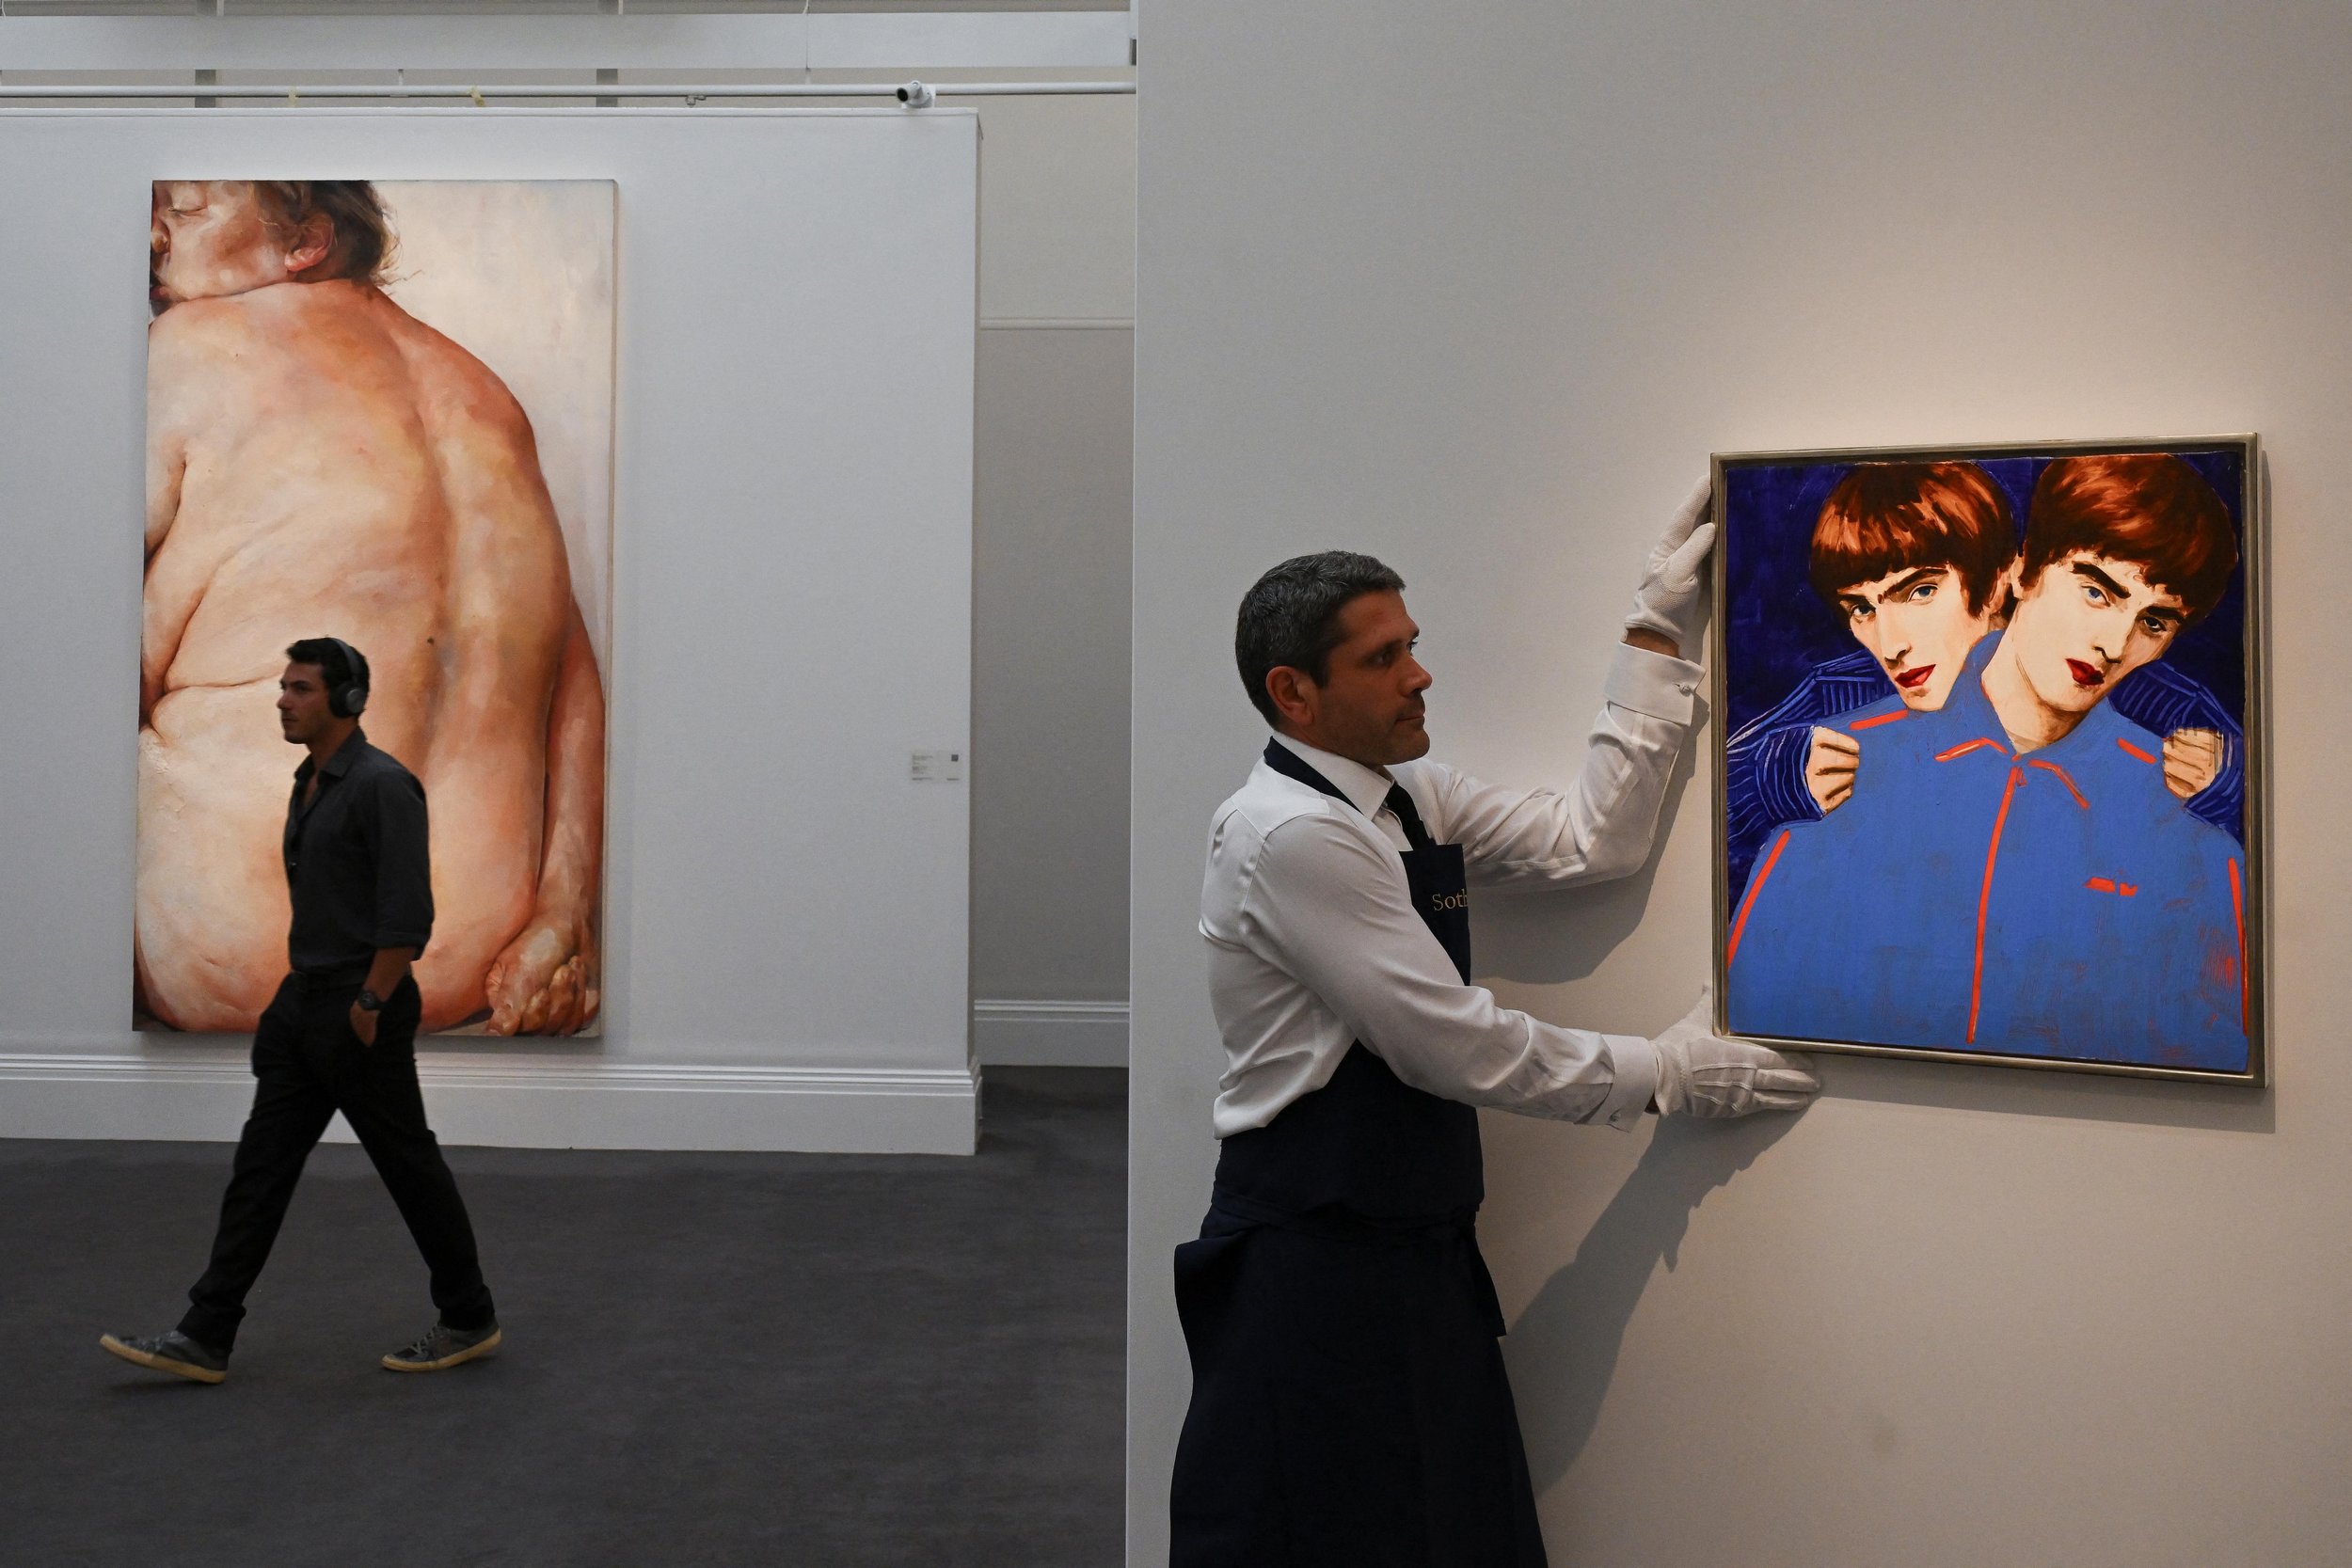
Artworks by Elizabeth Peyton and Jenny Saville on display at Sotheby's London ahead of its Modern and Contemporary Evening Auction in June 2025. Photograph: Jaimi Joy / Reuters.
The Hidden Economics of Transaction Costs
The financial difficulties associated with selling art extend beyond finding a buyer.
Transaction costs can significantly reduce an owner's realised return, particularly when an artwork has changed hands within a relatively short period.
At public auction, the buyer's premium is added to the hammer price, while the seller may pay an individually negotiated commission and additional expenses.
As of September 2026, both Christie's and Sotheby's published New York buyer's premium schedules beginning at 28% of the hammer price for the first $2 million, with lower percentage rates applying to higher price bands.
Consider a hypothetical painting purchased at auction with a hammer price of $100,000. At a 28% buyer's premium, its acquisition cost would be $128,000 before taxes, shipping and other expenses.
If the owner subsequently resold the same work for a hammer price of $100,000, the seller would already face a $28,000 difference between the original purchase cost and resale hammer price. Any seller's commission and related expenses would increase the loss.
The artwork's hammer price would have remained unchanged, yet the owner would have experienced a substantial negative investment return.
This calculation illustrates why rising auction prices do not automatically translate into profitable collecting.
Insurance, storage, conservation, transportation, restoration and financing costs may further affect the economics of ownership. Cross-border transactions can introduce additional administrative and tax considerations.
These expenses make short holding periods particularly vulnerable.
An artwork may need to appreciate meaningfully simply for its owner to recover the initial acquisition cost.
The financial case for collecting therefore depends not only on potential price appreciation, but on the relationship between holding periods, transaction expenses and the probability of successful resale.
Dealer Networks and the Importance of Finding the Right Buyer
For many collectors, resale takes place outside the auction room.
Established galleries and private dealers may introduce an artwork to collectors whose interests closely match its particular characteristics. Such transactions can provide discretion, flexible negotiation and greater control over the timing of a sale.
They can also avoid the public consequences of an unsuccessful auction.
Nevertheless, private transactions depend heavily on specialist relationships and market knowledge.
A dealer may understand which collectors are actively acquiring work by a particular artist, which institutions are developing relevant holdings and what price expectations are realistic.
This information is commercially valuable precisely because it is not widely available.
The 2026 Art Basel and UBS report estimated that dealer sales reached $34.8 billion in 2025, an increase of 2%. However, the average number of unique buyers per dealer declined to 57, its lowest level since 2021.
The figures illustrate how a large aggregate market can coexist with relatively concentrated networks of buyers.
For a collector attempting to resell, access to these networks may be more important than the existence of a recent auction record.
An artwork by a widely recognised artist may attract several potential buyers through an established international dealer network. An equally expensive work by a less extensively traded artist may depend on a small number of collectors whose purchasing interests can change.
This concentration creates vulnerability when owners need to sell quickly.
It also explains why relationships with reputable galleries can remain important long after the original acquisition.
Although galleries are not generally obliged to repurchase works they have sold, an established dealer may be better positioned than an unfamiliar intermediary to identify appropriate demand.
Why Auction Guarantees Do Not Eliminate Liquidity Risk
The increasing use of guarantees in major auctions has introduced another dimension to the liquidity debate.
An auction guarantee establishes a minimum financial commitment for an artwork before bidding begins. The arrangement may be provided by the auction house or an external party, sometimes through an irrevocable bid.
For sellers, guarantees can reduce uncertainty and provide greater confidence that a transaction will occur.
For auction houses, they can help secure important consignments and support ambitious sales.
Yet a guaranteed transaction should not automatically be interpreted as evidence of broad market demand.
A work may have a committed buyer without attracting substantial competitive bidding. The guarantee ensures a particular financial outcome, but it does not necessarily demonstrate that numerous independent buyers would purchase the artwork at the same price.
During the May 2026 New York auctions, reporting by international law firm Withers noted that many of the most valuable lots carried third-party irrevocable bids, reflecting the importance of prearranged financial commitments in high-value sales.
Such arrangements can improve liquidity for selected sellers, particularly owners of exceptional works.
However, comparable protection is rarely available across the entire market.
An artist whose work typically sells for £20,000 or £50,000 may have limited access to the sophisticated guarantee structures offered to consignors of major masterpieces.
Consequently, the most financially secure transactions can occur in precisely the market segments where wealthy collectors already possess the greatest flexibility.
The existence of guarantees should therefore be understood as evidence of increasingly sophisticated risk management, not proof that the underlying liquidity challenge has disappeared.
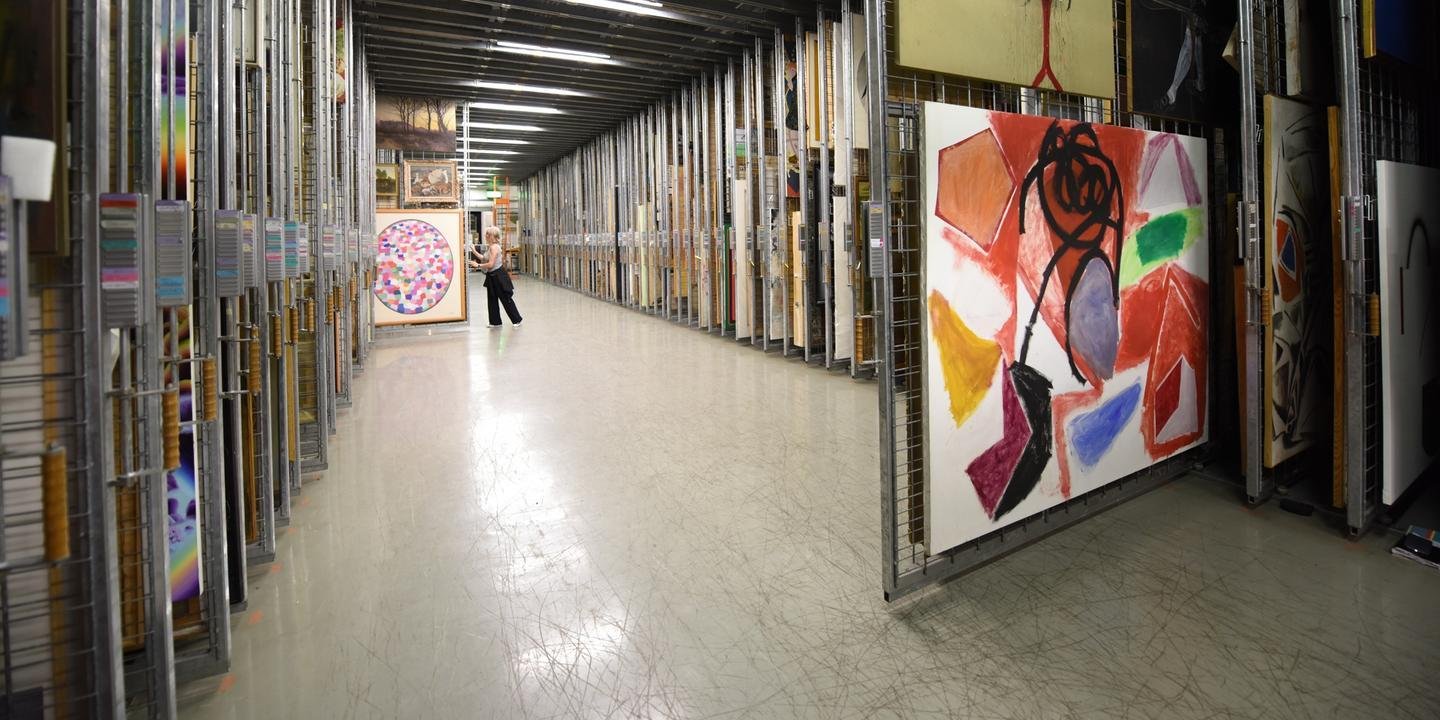
Artworks housed in a professional storage facility at the Centre national des arts plastiques in France, illustrating the practical responsibilities of preserving and managing art collections.
The Unequal Liquidity of Established and Emerging Artists
One of the clearest lessons from recent market performance is that price levels alone provide an inadequate measure of liquidity.
According to the Art Basel and UBS report, the value of fine art lots sold for more than $10 million increased by 30% in 2025, while both the value and volume of sales below $50,000 declined by 2%.
The value of transactions above $1 million increased by 21%, supported partly by important collections entering the market.
These figures demonstrate the uneven nature of the recovery, although aggregate sales values should not be confused with individual resale returns.
Established artists may benefit from extensive auction histories, institutional recognition and geographically diversified collector bases. Such characteristics can make demand easier to assess.
Emerging and ultra-contemporary artists often face greater uncertainty.
During periods of intense market interest, relatively limited supply can encourage rapid price increases. If demand subsequently weakens, collectors may discover that previous valuations depended on a narrow circle of buyers.
In its September 2026 market analysis, Bank of America Private Bank highlighted the sharp contraction in auction activity for younger contemporary artists during the first half of the year, contrasting it with more resilient performance among established categories.
Importantly, lower transaction volumes do not necessarily indicate equivalent declines in individual artwork prices. Fewer owners may be willing to sell, auction houses may become more selective and buyers may concentrate on particular artists.
Nevertheless, reduced market activity can make exits more difficult.
An artwork may retain significant cultural importance while becoming harder to sell at its previously quoted valuation.
Can Art Lending Provide an Alternative?
The development of art-backed lending offers one response to the liquidity problem.
Rather than selling artworks, collectors may use eligible works as collateral for loans, obtaining access to capital while retaining ownership.
This can be attractive when a collector expects stronger market conditions in the future or wishes to avoid an immediate sale.
Bank of America reported that its art loan commitments increased by 14% year-on-year during the first half of 2025, suggesting continued interest in financing arrangements secured against collections.
Yet borrowing against art does not eliminate the underlying liquidity risk.
Lenders generally assess collateral conservatively, considering authenticity, provenance, condition, marketability and the potential difficulty of resale.
Loan advances may represent only a portion of an artwork's appraised value.
Borrowers also face interest expenses and contractual obligations. If the value of the collateral declines or loan conditions are breached, a lender may require additional security or repayment.
Art lending can therefore provide temporary financial flexibility, but it should not be confused with converting an artwork into cash without risk.
For collectors, the suitability of borrowing depends on financing costs, liquidity requirements and the ability to meet obligations independently of future artwork appreciation.
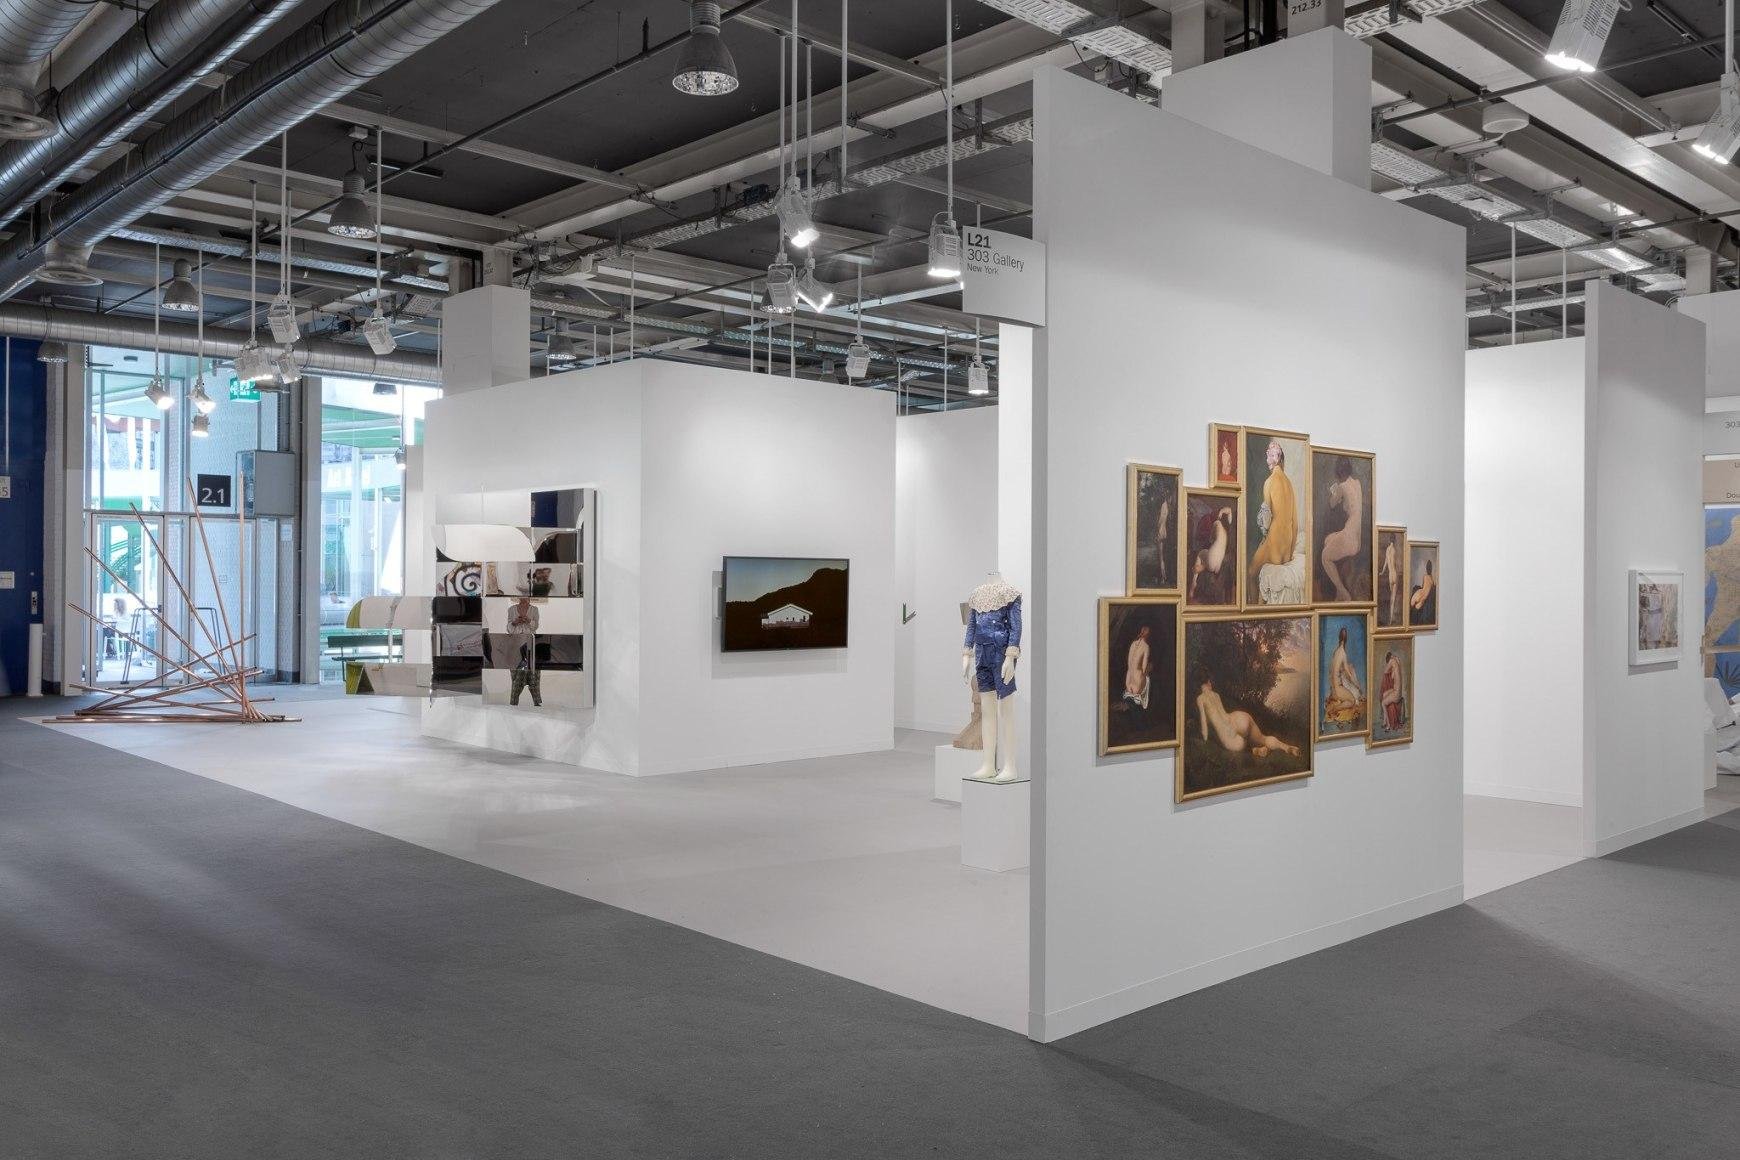
Installation view of 303 Gallery at Art Basel 2025, highlighting the role of international galleries in facilitating art sales and developing relationships with collectors. Photograph: Sebastiano Pellion di Persano.
What Could Change in 2027?
The outlook for 2027 depends on whether improving sales activity develops into broader, more consistent secondary-market demand.
Current evidence does not justify predicting a general liquidity crisis. The 2025 market recovery and stronger auction results during parts of 2026 demonstrate that substantial purchasing power remains available.
Nevertheless, several structural constraints are unlikely to disappear.
Artworks will remain heterogeneous assets traded through fragmented networks. Valuations will continue to depend on incomplete information. Transaction costs will remain significant, and buyers will retain considerable discretion over when and what they acquire.
More sophisticated market data may improve pricing transparency, but digital information cannot create demand where none exists.
Auction houses and dealers may increasingly prioritise realistic estimates, carefully managed consignments and pre-sale negotiations to improve transaction certainty.
Collectors, meanwhile, may place greater emphasis on the depth of an artist's secondary market, the continuity of gallery representation and the diversity of potential buyers.
These are plausible developments rather than established outcomes for 2027.
A more liquid art market would require stronger price discovery, greater transparency and more extensive buyer participation. Whether commercial institutions can deliver these improvements without compromising the distinctive qualities of the art trade remains an open question.
Conclusion: The Price of an Artwork Is Not the Price of an Exit
The international art market's liquidity problem is not simply a consequence of economic uncertainty. It is embedded in the structure of a market where each object is unique, transactions are irregular and information remains unevenly distributed.
Recent auction recoveries demonstrate that significant capital continues to circulate, but they do not establish that every collector can sell successfully when circumstances require.
For owners, the distinction between estimated value and achievable proceeds is fundamental.
A work acquired for its cultural significance may remain rewarding regardless of market conditions. An artwork purchased partly for financial appreciation demands a more demanding assessment of resale prospects, holding costs and potential losses.
As 2027 approaches, greater attention to liquidity could encourage a more disciplined approach to collecting and valuation.
The most useful question may no longer be how much an artwork could achieve under ideal auction conditions, but what price a credible buyer would offer, after costs, within a realistic period.
Ultimately, the financial value of art is not fully demonstrated when a collector purchases it. That value is tested when ownership must change hands.